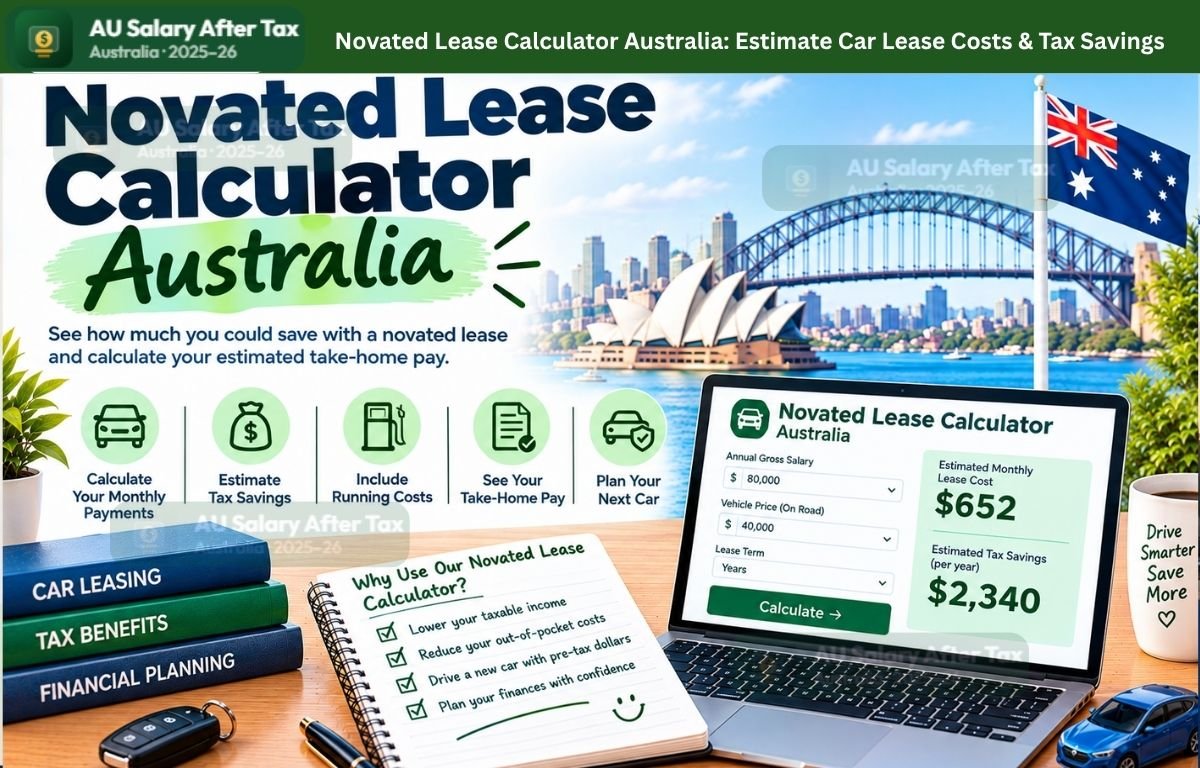
A novated lease lets you pay for a car — the lease plus fuel, insurance, servicing and rego — from your pre-tax salary. On a $100,000 salary, packaging $12,000 of car costs can save around $3,840 a year in tax. The Novated Lease Calculator Australia estimates that saving in seconds.
But read its headline number carefully: the calculator quietly assumes you have a HELP debt and uses outdated HECS rates, which inflates its “tax saved” figure by about $1,500 a year for anyone without a study debt. It also doesn’t model FBT, the EV exemption, GST savings or residuals at all. This guide gives you the honest maths: how novated leasing really works, five worked examples with verified figures, the FBT rules that make or break the deal, and exactly where the calculator misleads you.
Table of Contents
Important: Figures use 2025–26 Australian tax and super rules. This is general information, not personal financial advice. Novated leases are a major financial commitment; consider licensed advice before signing.
What Is the Novated Lease Calculator Australia?
A novated lease is a three-way agreement between you, your employer and a finance company: you choose the car, the finance company leases it to you, and your employer takes over the lease payments — deducting them from your pre-tax salary through salary packaging. Your taxable income drops, so you pay less income tax, and the employer can claim GST credits on the lease and running costs.
The calculator answers the practical question: “if I package $X of car costs on my $Y salary, how much tax do I save and what’s the car’s real after-tax cost?” It compares your tax with and without packaging and shows the saving.
Who should use it:
- Employees whose employer offers salary packaging, weighing up a novated lease
- Anyone comparing a novated lease against buying a car outright or with a regular car loan
- EV buyers checking how the FBT exemption changes the maths
- People who’ve been quoted a novated lease and want an independent sense of the tax saving
Important: The calculator’s estimate covers income tax only (plus a hidden HECS assumption — see below). It does not model FBT, the EV exemption, GST savings or the residual payment. Treat it as a starting estimate, not a quote.
What Does the Novated Lease Calculator Do?
The Novated Lease Calculator Australia keeps it simple — three inputs in, a full breakdown out.
| Input | What to enter |
|---|---|
| Annual Salary | Your gross annual salary before packaging (default $100,000) |
| Annual Lease Cost | The year’s finance payments including interest and fees, as quoted by the lease provider (default $8,000) |
| Annual Running Costs | Fuel/charging, registration, insurance, servicing, tyres (default $4,000) |
| Output | What it means |
|---|---|
| Annual Tax Saved (hero) | The calculator’s estimate of tax saved — overstated if you have no HELP debt |
| Total Packaged Amount | Lease cost + running costs |
| Tax Before / After Packaging | Total “tax” on full salary vs reduced salary — includes phantom HECS |
| Effective After-Tax Cost | Packaged amount minus tax saved |
| Take-Home (Without / With Lease) | What lands in your bank account either way |
How to Use the Novated Lease Calculator
Step 1 — Enter your annual salary. Your gross salary before any packaging, not including super.
Step 2 — Enter the annual lease cost. The total finance payment for the year — interest and fees included — exactly as your lease provider quotes it. If they quote monthly, multiply by 12.
Step 3 — Enter annual running costs. Everything the budget covers: fuel or charging, registration, insurance, servicing, tyres. Be realistic — underestimating this is the most common mistake.
Step 4 — Read “Effective After-Tax Cost”, not just the headline. The big “TAX SAVED” number is inflated (explained below). The effective after-tax cost tells you what the car truly costs you per year.
How Novated Leasing Works — the Three-Way Deal
Three parties, one car:
- You choose the car (new or used, subject to the lender’s rules) and the lease term.
- The finance company buys the car and leases it to you.
- Your employer “novates” the lease — legally taking on your payment obligations — and deducts the lease plus a running-cost budget from your pre-tax salary each pay.
Two tax advantages flow from this:
- Income tax: your taxable income falls by the packaged amount, so you pay less tax. At a 32% marginal rate (30% + 2% Medicare), every $1,000 packaged saves $320.
- GST: your employer claims GST credits on the lease payments and running costs (1/11th of the GST-inclusive cost), and that saving is passed to you in the packaging — something you can’t get buying privately.
At the end of the lease term you pay the residual (balloon payment) — a lump sum set as a percentage of the car’s price — and the car is yours. Or you can refinance, trade in, or hand it back depending on the agreement.
Read more: Salary Sacrifice Calculator Australia: Complete Guide to Salary Sacrifice, Super and Tax Savings
Worked Examples
All figures below use correct 2025–26 maths. Each example shows what the calculator displays — and where it diverges.
Example 1 — $100,000 salary, $12,000 packaged (the calculator’s defaults)
| Figure | |
|---|---|
| Salary | $100,000 |
| Packaged (lease $8,000 + running $4,000) | $12,000 |
| Tax before (income tax $20,788 + Medicare $2,000) | $22,788 |
| Tax after ($88,000: $17,188 + $1,760) | $18,948 |
| True tax saved | $3,840 |
| Effective after-tax cost | $8,160 |
The calculator shows “Tax Saved: $5,380” — $1,540 too high. Why? It silently adds HECS/HELP repayments (at outdated 2023–24 rates: 5.5% at $100,000, 4.5% at $88,000) as if you have a study debt. With no HELP debt, the real saving is 32% × $12,000 = $3,840, and the car’s true after-tax cost is $8,160, not the $6,620 the calculator shows.
Example 2 — $80,000 salary, $12,000 packaged
| Figure | |
|---|---|
| Salary | $80,000 |
| Packaged | $12,000 |
| Tax before ($14,788 + $1,600) | $16,388 |
| Tax after ($68,000: $11,188 + $1,360) | $12,548 |
| True tax saved | $3,840 |
| Effective after-tax cost | $8,160 |
Same $3,840 — the whole $12,000 sits in the 30%-plus-Medicare bracket. The calculator shows $5,340, overstated by $1,500 for anyone without a HELP debt (it bakes in 4.0% HECS at $80,000 and 2.5% at $68,000 under the old rates).
Example 3 — EV on $100,000 salary, $20,000 packaged (FBT-exempt)
| Figure | |
|---|---|
| Salary | $100,000 |
| Packaged (eligible EV — no FBT) | $20,000 |
| Tax before | $22,788 |
| Tax after ($80,000: $14,788 + $1,600) | $16,388 |
| Tax saved | $6,400 |
| Effective after-tax cost | $13,600 |
Eligible electric vehicles are FBT-exempt (conditions below), so the full 32% marginal benefit applies with no FBT to neutralise: 32% × $20,000 = $6,400. This is where novated leasing shines brightest.
Example 4 — $50,000 petrol car: the FBT bill the calculator ignores
A $50,000 petrol car under the statutory formula has a taxable value of 20% × $50,000 = $10,000 per FBT year. Unmitigated FBT = $10,000 × 2.0802 (Type 1 gross-up) × 47% = $9,776.94 per year — more than wiping out the income-tax saving.
In practice, leases are structured with the Employee Contribution Method: you make $10,000 of post-tax contributions, the taxable value falls to nil, and FBT is $0. But those post-tax contributions come from after-tax dollars — the calculator models none of this.
Example 5 — the residual on a 5-year lease
ATO minimum residuals: 12 months 65.63%, 24 months 56.25%, 36 months 46.88%, 48 months 37.50%, 60 months 28.13%. On a $50,000 car over 5 years, the residual is 28.13% × $50,000 = $14,065 (plus GST, payable by you). Budget for it from day one — it’s the most underestimated part of a novated lease.
What the Calculator Gets Wrong
The calculator’s core comparison (tax on full salary vs reduced salary) is arithmetically sound — but it has four problems:
1. The phantom HECS assumption. Its “total tax” silently includes HECS/HELP repayments at outdated 2023–24 rates, assuming you have a study debt. There’s no HECS input and no disclosure. If you don’t have a HELP debt, “tax saved” is overstated by about $1,500 a year — and the take-home figures are understated too.
2. Its own guide examples don’t reconcile. The page’s $95,000-salary example claims tax of “about $22,067” before packaging and “about $17,547” after — but the calculator’s own formula gives neither figure (with or without the HECS assumption). Same for the $140,000 example ($38,347/$31,147). Don’t try to reproduce them; use the calculator’s live outputs instead.
3. FBT isn’t modelled at all. The page admits this (“does not model FBT in detail”), but FBT is the single biggest variable in a novated lease — $9,777 a year on a $50,000 petrol car if unmitigated. A calculator that ignores it while showing a confident “tax saved” hero number is telling half the story.
4. No EV toggle, no ECM split, no GST, no residual. The EV FBT exemption, the pre-tax/post-tax contribution split, GST credits and the balloon payment all materially change the answer — none are inputs. The tool is a packaging estimator, not a lease comparison.
FBT and Novated Leases — the 47% Problem
When your employer provides a car benefit, Fringe Benefits Tax can apply at 47% — and it’s levied on the grossed-up taxable value, which makes it brutal:
Taxable value (statutory method) = base value × 20% × (days available ÷ days in FBT year) − employee contribution
FBT = taxable value × 2.0802 (Type 1 gross-up) × 47%
The 20% statutory rate applies to all commitments after 10 May 2011. The FBT year runs 1 April to 31 March — not the financial year.
The industry-standard fix is the Employee Contribution Method (ECM): you make post-tax contributions equal to the taxable value, reducing it to nil and the FBT to zero. The lease is then structured so the FBT cost is “neutralised” — but remember those contributions come from after-tax dollars, which shrinks the headline tax saving.
Read more: Best Income Tax Calculator Australia 2025–26: Complete Guide
Electric Vehicles — the FBT Exemption
Since 1 July 2022, eligible electric cars are FBT-exempt — no FBT at all, no ECM needed. Conditions (all must hold):
- Battery electric or hydrogen fuel-cell vehicle (not a plug-in hybrid — PHEVs were excluded from 1 April 2025, with grandfathering only for pre-existing binding commitments)
- First held and used on or after 1 July 2022
- Luxury car tax has never been payable on it — i.e. under the fuel-efficient LCT threshold ($91,387 for 2025–26; $91,661 for 2026–27)
This is why EV novated leases are so popular: Example 3’s $6,400 saving comes with zero FBT structuring. Two warnings:
- The exemption is being wound back (announced, not yet law). Announced 5 May 2026: full exemption continues to 31 March 2027; from 1 April 2027 only EVs up to $75,000 stay fully exempt ($75,000–LCT threshold gets a 25% FBT discount); from 1 April 2029 all eligible EVs get the 25% discount instead. Existing leases are grandfathered. Treat this as proposed until legislated.
- Reportable fringe benefits still apply — even FBT-exempt EVs generate a reportable amount on your payment summary (see below).
The GST Saving
One genuine advantage the calculator doesn’t quantify: your employer claims GST credits on the lease payments and running costs, and the saving flows to you.
- GST credit = 1/11th of the GST-inclusive cost (e.g. ~$1,818 a year on $20,000 of packaged costs).
- The car limit ($69,674 for 2025–26) caps the GST credit on the car’s purchase price at $6,334 — running-cost GST is uncapped.
- You pay GST on the residual when you buy the car at lease end.
Someone packaging $20,000 a year keeps roughly $1,800 of GST they’d otherwise pay buying privately — on top of the income-tax saving.
Residuals and End of Lease
The ATO sets minimum residual values — the balloon can’t be set lower (a lower residual would be a tax-avoidance red flag):
| Lease term | Minimum residual |
|---|---|
| 12 months | 65.63% |
| 24 months | 56.25% |
| 36 months | 46.88% |
| 48 months | 37.50% |
| 60 months | 28.13% |
At lease end you can pay the residual and keep the car, refinance it into a new lease, or sell/trade the car (any shortfall or surplus is generally yours to manage). The trap: a 5-year lease on a $50,000 car leaves a $14,065 balloon — if the car’s market value has fallen below that, you’re covering the gap.
Reportable Fringe Benefits — the Hidden Cost
If the taxable value of your fringe benefits exceeds $2,000, the grossed-up amount appears on your payment summary as a Reportable Fringe Benefits Amount (RFBA). It isn’t taxed directly — but it’s added to your income for:
- HELP repayment income (bigger compulsory repayments)
- Medicare levy surcharge thresholds
- Division 293 ($250,000 test)
- Family payments and child support
On a $50,000 FBT-exempt EV: RFBA = $10,000 × 2.0802 = $20,802 added to those tests. A novated lease can quietly push you over thresholds you’d otherwise stay under — model it, especially if you’re near the Division 293 line.
Read more: HECS Calculator Australia: Complete Guide to HECS-HELP Repayments, Thresholds and Rates
What Happens If You Change Jobs
The novation is with your employer — leave the job and it ends. Typically you must:
- Take over the lease yourself (payments come from after-tax dollars — the tax benefit stops immediately),
- Transfer it to a new employer (only if they offer salary packaging),
- Refinance or pay out the lease (financial termination can trigger fees and an early residual calculation).
Never sign a novated lease without knowing the exit terms. Job mobility is the biggest non-tax risk in the whole arrangement.
Novated Lease vs Buying Outright
| Novated lease | Buying outright | |
|---|---|---|
| Tax saving | Pre-tax packaging (32% marginal typical) | None |
| GST | Employer claims credits, passed to you | You pay full GST |
| FBT | Must be managed (ECM) or exempt (EV) | None |
| Residual risk | Balloon payment at end | You own it outright |
| Flexibility | Tied to your employer | Sell anytime |
| Running costs | Bundled, budgeted, pre-tax | After-tax, your problem |
A novated lease usually wins for eligible EVs and for disciplined drivers who’d spend the running costs anyway. It loses when FBT is mismanaged, when you change jobs mid-lease, or when the car depreciates faster than the residual assumes.
Common Mistakes
- Trusting the calculator’s “tax saved” with no HELP debt — it’s ~$1,500 overstated; the true figure is 32% of the packaged amount at the 30% bracket.
- Ignoring FBT on petrol/diesel cars — $9,777 a year unmitigated on a $50,000 car; ECM structuring is not optional.
- Forgetting the residual — $14,065 on a 5-year $50,000 lease; budget for the balloon from day one.
- Assuming a PHEV is FBT-exempt — plug-in hybrids were excluded from 1 April 2025.
- Missing the RFBA impact — $20,802 on a $50,000 EV can tip HELP, MLS or Division 293 calculations.
- Underestimating running costs — the budget is fixed; blowouts come from your pocket.
- Not checking job-change terms — the tax benefit dies the day the novation ends.
- Buying over the LCT threshold — kills the EV exemption and caps your GST credit.
Practical Tips
- Get the lease quote first, then model — use the provider’s annual finance figure as the lease-cost input, not a guess.
- Subtract ~$1,500 from the calculator’s saving if you have no HELP debt — that’s the honest number.
- For petrol cars, confirm ECM structuring in writing — “FBT neutralised” should appear in the quote.
- For EVs, confirm FBT-exempt eligibility — BEV, under the LCT threshold, first used after 1 July 2022.
- Price the residual into your decision — compare the balloon against realistic resale values.
- Check your employer’s packaging policy — not all employers offer novated leases, and some restrict vehicle types or providers.
How much tax can I save with a novated lease?
Roughly your marginal rate times the packaged amount: at the 30% bracket plus 2% Medicare, that’s 32% — $3,840 a year on $12,000 packaged. The calculator shows about $1,500 more because it assumes a HELP debt; subtract that if you don’t have one.
Does my employer have to offer novated leasing?
No. Salary packaging is voluntary for employers. If yours doesn’t offer it, there’s no way to novate — ask about their packaging policy before getting quotes.
What happens to my novated lease if I change jobs?
The novation ends with your employment. You take over the payments yourself (losing the tax benefit), transfer the novation to a new employer if they offer packaging, or refinance/pay out the lease — which can trigger termination fees.
Are electric vehicles better for novated leasing?
Usually yes: eligible EVs are FBT-exempt, so there’s no 47% FBT to neutralise and no ECM needed. Conditions: battery electric (PHEVs excluded since 1 April 2025), under the $91,387 LCT threshold, first used after 1 July 2022. Note the announced wind-back from April 2027.
Does a novated lease affect my superannuation?
Your SG is calculated on your ordinary earnings and shouldn’t fall just because you package — but check your employment contract, because some employers calculate SG on the reduced post-packaging salary. Your take-home pay falls either way, so review any salary-linked insurance inside super too.
Can I novated lease a used car?
Yes, if it meets the lender’s age and value criteria — most providers cap the car’s age at lease end (commonly 10–12 years). The same FBT, residual and GST rules apply.
What is the Employee Contribution Method?
You make post-tax contributions equal to the car’s FBT taxable value (e.g. $10,000 on a $50,000 car at the 20% statutory rate), reducing the taxable value — and the FBT — to nil. It’s how petrol-car leases avoid the 47% FBT bill, at the cost of using after-tax dollars.
What is the residual (balloon payment)?
The lump sum due at lease end, set as a percentage of the car’s price — minimum 28.13% on a 5-year lease ($14,065 on $50,000). You pay it to own the car, refinance it, or settle it from the car’s sale proceeds.
Do novated lease benefits show on my payment summary?
Yes, as a Reportable Fringe Benefits Amount if the taxable value exceeds $2,000 — even for FBT-exempt EVs ($20,802 on a $50,000 EV). It’s not taxed directly but counts toward HELP repayments, the Medicare surcharge, Division 293 and family payments.
Is the calculator’s “tax saved” figure accurate?
Only if you have a HELP debt — and even then it uses outdated 2023–24 HECS rates. Without a study debt, subtract about $1,500 from its figure: the true saving is your marginal rate (typically 32%) times the packaged amount. It also ignores FBT, GST savings and the residual entirely.
Final Takeaway
The honest formula:
True annual saving = marginal tax rate × packaged amount (32% at the 30% bracket)
True after-tax cost = packaged amount − true saving + any FBT + residual provision
Use the Novated Lease Calculator Australia for a quick packaging estimate — then subtract ~$1,500 if you have no HELP debt, add FBT unless the car is an eligible EV, and never forget the balloon. Done right, a novated lease is one of the best tax breaks available to employees; done blindly, the FBT and residual can eat the whole saving.