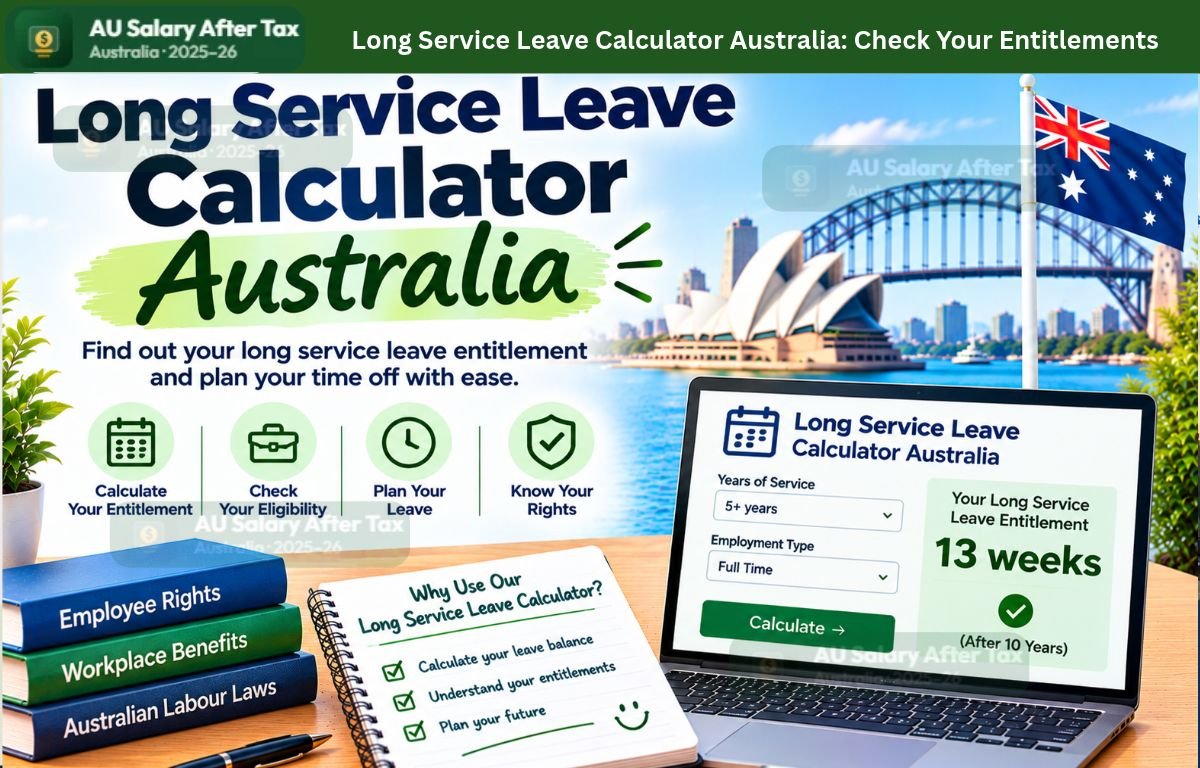
Ten years with one employer is a long time. Long service leave is the reward for it: a block of paid leave that, on an $80,000 salary, is worth more than $13,000 in most states — and $20,000 in South Australia and the Northern Territory. The long service leave calculator Australia workers use on this page turns two numbers — your annual salary and your years of service — into an estimate of that entitlement in weeks, days and dollars.
This long service leave calculator Australia guide explains where that number comes from, why the same salary and service can be worth very different amounts in different states, how a payout is taxed in 2026–27, and the mistakes that cost people thousands when they leave a job. It also corrects the calculator where its numbers are wrong — most seriously for South Australia and the Northern Territory, where it understates a 10-year entitlement by more than $6,600.
Important: All figures in this guide are for 2026–27 unless a year is stated. Long service leave is set by state and territory law, not the federal Fair Work Act, so the figures that matter are your state’s. The calculator uses one accrual rate — 0.867 weeks per year — for every state. That rate is right for New South Wales, Victoria, Queensland, Western Australia, Tasmania and the ACT, but it is wrong for South Australia and the Northern Territory, where the rate is 1.3 weeks per year. The worked examples below use the correct rate for each state.
Table of Contents
What Is the Long Service Leave Calculator?
The long service leave calculator estimates the dollar value of the long service leave you have accrued with one employer. It is an estimate of one entitlement only — not a full final-payslip calculation, and it cannot tell you whether your state lets you take the leave yet, or pay it out if you leave.
It takes just two inputs:
| Input | What to enter | Default |
|---|---|---|
| Annual Salary | Your gross annual salary before tax, not including superannuation | $80,000 |
| Years of Service | Your completed years of continuous service with the same employer | 10 |
It returns a four-row breakdown:
| Output | What it means |
|---|---|
| Weekly Pay | Annual salary ÷ 52 |
| Est. Leave Entitlement | Accrued weeks of long service leave (years × 0.867) |
| Est. Leave Value | Accrued weeks × weekly pay |
| Note | “Varies by state & award” |
With the default inputs — $80,000 salary and 10 years of service — the calculator shows weekly pay of $1,538.46, an entitlement of 8.7 weeks (about 43 days), and a leave value of $13,338.46. That figure is right for New South Wales, Victoria, Queensland, Western Australia and Tasmania. It is wrong for South Australia and the Northern Territory, where the same 10 years is worth 13 weeks and $20,000.
Read more: Annual Leave Calculator Australia: Complete Guide to Annual Leave, Leave Loading and Your Payout
Long Service Leave Calculator Australia: How to Use It
Using the calculator takes less than a minute, but the two numbers you enter — and the state you work in — decide what its answer is worth.
- Enter your annual salary. Use your base salary — your ordinary rate for your ordinary hours, before tax and before superannuation. Do not include overtime, bonuses or one-off allowances. If you are part-time, enter your actual part-time annual salary, not the full-time equivalent.
- Enter your completed years of continuous service. Only service with the same employer counts, and only continuous service. A break can reset the clock in some states, and unpaid leave usually does not count towards the total even when it does not break continuity.
- Read the weeks, not just the dollars. The dollar figure is only as good as the weeks figure behind it. Check the weeks against your state’s rate in the table below before relying on the value.
Use it with these limitations in mind:
- It uses one accrual rate for the whole country. South Australia and the Northern Territory accrue at 1.3 weeks a year, not 0.867 — the calculator understates every entitlement there by about a third.
- It has no state input. It cannot tell you whether you can take leave yet, or whether a pro-rata payout is payable if you resign.
- It does not model portable schemes. In building and construction, contract cleaning, community services and security, leave may accrue with an industry scheme across employers.
- It computes no tax. The dollar value is gross. How much of a payout you keep depends on why you left, when the leave accrued, and your total income for the year.
How Long Service Leave Is Calculated
Three steps turn your salary and service into a dollar value, and the long service leave calculator Australia workers use follows exactly these steps:
Weekly pay = annual salary ÷ 52
Accrued weeks = years of service × your state’s accrual rate
Leave value = accrued weeks × weekly pay
The accrual rate is where the states split. Six jurisdictions accrue at 0.8667 weeks a year — one week of leave for every 60 weeks of service, or 8⅔ weeks after 10 years. Two accrue at 1.3 weeks a year — 13 weeks after 10 years.
| Years of service | Weeks at 0.8667 a year (NSW, VIC, QLD, WA, TAS, ACT) | Weeks at 1.3 a year (SA, NT) |
|---|---|---|
| 5 years | 4.33 weeks | 6.50 weeks |
| 7 years | 6.07 weeks | 9.10 weeks |
| 10 years | 8.67 weeks | 13.00 weeks |
| 15 years | 13.00 weeks | 19.50 weeks |
| 20 years | 17.33 weeks | 26.00 weeks |
Working days are weeks × 5 for a five-day worker. So 8.67 weeks is about 43 working days, and 13 weeks is 65 working days — roughly three months of paid leave.
Note the rate the calculator actually uses: 0.867, a rounded version of 0.8667. The rounding is small, but it is not free. On an $80,000 salary with 10 years of service the calculator shows $13,338.46; the exact statutory figure is $13,333.33 — a $5.13 overstatement.
Long Service Leave by State and Territory
This is the table the whole guide turns on. Long service leave is state law, so there is no national figure — only eight sets of rules. The Fair Work Ombudsman confirms the point plainly: most employees’ long service leave comes from the laws of their state or territory, which set how long you must work and how much leave you get. (Fair Work Ombudsman – Long service leave)
| State / Territory | Law | Full entitlement | Can take leave from | Pro-rata payout from |
|---|---|---|---|---|
| New South Wales | Long Service Leave Act 1955 | 8.67 weeks at 10 years; + 4.33 weeks per further 5 years | 10 years | 5 years, qualifying reasons only |
| Victoria | Long Service Leave Act 2018 | 1/60th of service; 6.07 weeks at 7 years; 8.67 weeks at 10 years | 7 years | 7 years, on any termination |
| Queensland | Industrial Relations Act 2016 | 8.67 weeks at 10 years; + 4.33 weeks per further 5 years | 10 years | 7 years, qualifying reasons only |
| South Australia | Long Service Leave Act 1987 | 13 weeks at 10 years; + 1.3 weeks per year after | 10 years | 7 years, on most endings |
| Western Australia | Long Service Leave Act 1958 | 8.67 weeks at 10 years; + 4.33 weeks per further 5 years | 10 years | 7 years, on any termination |
| Tasmania | Long Service Leave Act 1976 | 8.67 weeks at 10 years; + 4.33 weeks per further 5 years | 10 years | 7 years, qualifying reasons only |
| Australian Capital Territory | Long Service Leave Act 1976 | 6.07 weeks at 7 years; + 1/5 month per year after | 7 years | 5 years, qualifying reasons only |
| Northern Territory | Long Service Leave Act 1981 | 13 weeks at 10 years; + 1.3 weeks per year after | 10 years | 7 years, qualifying reasons only |
“Qualifying reasons only” is the phrase that catches people out. In those states, a pro-rata payout before the full qualifying period is not automatic. It is payable only if the employment ends in a way the Act lists — and an ordinary resignation is usually not on that list.
New South Wales. Two months (8.67 weeks) after 10 years, then a further month (4.33 weeks) for each additional 5 years. The Act covers full-time, part-time and casual workers. Pro-rata after 5 years applies if you resign because of illness, incapacity, or domestic or other pressing necessity; if you are dismissed for any reason except serious and wilful misconduct; or if you die. After 10 years, accrued leave is payable on termination for any reason. Pay is based on the higher of your ordinary pay for the last pay period, or your average weekly pay over the previous five years.
Victoria. You accrue 1/60th of your total continuous employment from day one, and you can take leave after 7 years — about 6.07 weeks at that point. After 7 years, accrued leave is also payable as a pro-rata payout if your employment ends, including on an ordinary resignation. The Act covers casuals, seasonal employees, trainees and apprentices. Paid or unpaid parental leave does not break continuity, and the first 52 weeks of unpaid parental leave count towards accrual.
Queensland. Under the Industrial Relations Act 2016, you get 8.6667 weeks after 10 years, then a further 4.3333 weeks for each additional 5 years. You cannot take leave at 7 years — 7 years only opens a pro-rata payout window on termination, and only for listed reasons: dismissal for any reason other than serious misconduct (including redundancy), resignation because of illness, incapacity or domestic or other pressing necessity, or death. An ordinary resignation between 7 and 10 years gets nothing. After 10 years, payment on termination is automatic.
South Australia. Thirteen weeks after 10 years, then 1.3 weeks (9.1 days) for each year after that. A pro-rata payment is available once you complete 7 years, equal to 1.3 weeks for each completed year of service. It is generally payable on most endings — resignation, redundancy, retirement or dismissal — but not if you are terminated for serious and wilful misconduct. Since 1 October 2025, community services workers are also covered by a portable scheme.
Western Australia. Under the Long Service Leave Act 1958, you get 8.6667 weeks after 10 years, then a further 4.333 weeks for each additional 5 years. Its pro-rata rule is the most generous after Victoria’s: if your employment ends after at least 7 years but less than 10, you are entitled to a pro-rata payment regardless of the reason it ended — including an ordinary resignation. The exception is dismissal for serious misconduct.
Tasmania. Under the Long Service Leave Act 1976, you get 8⅔ weeks after 10 years, then 4⅓ weeks for each additional 5 years. A pro-rata payment is available after 7 years, calculated as your years of service divided by 10, multiplied by 8.667 weeks — but only in certain circumstances, such as employer termination for a reason other than serious misconduct, resignation because of illness, incapacity or domestic or other pressing necessity, retirement at the qualifying age, or death. Mining employees are covered separately, with 13 weeks per 10 years.
Australian Capital Territory. Under the Long Service Leave Act 1976, you get 6.0667 weeks after 7 years, then a further one-fifth of a month for each year after that. A pro-rata payment is available after 5 years if the employment ends in listed circumstances, including employer termination for any reason other than serious and wilful misconduct, resignation because of illness, incapacity or domestic or other pressing necessity, or retirement at the minimum retiring age. Commonwealth public servants are covered separately, generally with 13 weeks after 10 years.
Northern Territory. Under the Long Service Leave Act 1981, you get 13 weeks after 10 years, then 1.3 weeks for each year after that. A pro-rata payment is available after 7 years, but only for completed years of service — 8½ years pays for 8 years — and only if the employment ends because of retirement, illness, incapacity or domestic or other pressing necessity, or employer termination for a reason other than serious misconduct. Long service leave cannot be cashed out while you are still employed.
Pro-Rata Long Service Leave: Who Gets Paid When Employment Ends
The pro-rata rules are where most long service leave money is lost. Two employees with the same service can get very different outcomes, because the reason the job ended decides whether anything is payable at all.
| How employment ends | NSW (5+ yrs) | VIC (7+ yrs) | QLD (7–10 yrs) | SA (7+ yrs) | WA (7+ yrs) | TAS (7–10 yrs) | ACT (5–7 yrs) | NT (7–10 yrs) |
|---|---|---|---|---|---|---|---|---|
| Ordinary resignation | No | Yes | No | Yes | Yes | No | No | No |
| Resignation for illness, incapacity or domestic necessity | Yes | Yes | Yes | Yes | Yes | Yes | Yes | Yes |
| Dismissal, except serious misconduct | Yes | Yes | Yes | Yes | Yes | Yes | Yes | Yes |
| Dismissal for serious misconduct | No | No | No | No | No | No | No | No |
| Redundancy | Yes | Yes | Yes | Yes | Yes | Yes | Yes | Yes |
| Death | Yes | Yes | Yes | Yes | Yes | Yes | Yes | Yes |
| Retirement | No, unless illness or necessity | Yes | No, unless illness or necessity | Yes | Yes | Yes, at qualifying age | Yes, at minimum retiring age | Yes |
Three points deserve emphasis. First, Victoria, Western Australia and South Australia are the states where an ordinary resignation after 7 years attracts a pro-rata payout. Second, in New South Wales and the ACT the window opens at 5 years, not 7 — the earliest in the country. Third, once you pass the full qualifying period (10 years in most states, 7 in Victoria and the ACT), the reason stops mattering: accrued leave is payable on termination for any reason.
If you are thinking of resigning, the table is worth more than the calculator. Leaving at 9 years instead of 10 can mean forfeiting the whole entitlement in Queensland, Tasmania and the Northern Territory if your reason is an ordinary resignation — while the same resignation in Victoria, Western Australia or South Australia would be paid in full.
Read more: Redundancy Pay Calculator Australia: Complete Guide to Redundancy Pay, Tax and Your Final Payout
Long Service Leave Calculator Australia: Worked Examples
Every example below uses 2026–27 figures and the correct rate for the state named. Weeks are shown rounded to two decimals. Where an example is the calculator page’s own, the dollar value is the calculator’s figure and the exact statutory figure is stated alongside it; multiplying the rounded weeks by the rounded weekly pay can differ from the stated value by a few cents.
Example 1: $80,000 salary, 10 years in New South Wales (the calculator default)
- Weekly pay: $80,000 ÷ 52 = $1,538.46
- Accrued leave: 10 × 0.8667 = 8.67 weeks (about 43 working days)
- Leave value: 8.67 × $1,538.46 = $13,338.46
The calculator shows exactly this figure. Its rounded rate costs you $5.13 against the exact statutory value of $13,333.33. In South Australia or the Northern Territory, the same salary and service is worth 13 weeks and $20,000 — the calculator understates it by $6,661.54.
Example 2: $85,000 salary, 12 years of service
- Weekly pay: $85,000 ÷ 52 = $1,634.62
- Accrued leave: 12 × 0.8667 = 10.40 weeks
- Leave value: 10.404 × $1,634.62 = $17,006.54
This is the page’s own example, and its arithmetic is correct — the page says “about $17,000”, and the exact statutory figure is $17,000.00. In South Australia or the Northern Territory, 12 years at this salary is worth 15.6 weeks and $25,500.00.
Example 3: $78,000 salary, 10 years in New South Wales — and the tax, done properly
- Weekly pay: $78,000 ÷ 52 = $1,500.00
- Accrued leave: 10 × 0.8667 = 8.67 weeks
- Leave value: 8.67 × $1,500 = $13,005.00
At the exact statutory rate the payout would be $13,000.00 — $5.00 less than the calculator’s $13,005.00 — so the tax analysis below uses the page’s own $13,005.00 figure.
The page says this payout is “taxed at a 30% marginal rate plus Medicare, roughly $4,000 in tax, leaving about $9,000 net”. That is wrong in two ways. First, on the page’s own facts it understates the tax: if the payout sits on top of a full $78,000 year, taxable income becomes $91,005. Income tax rises from $13,920.00 to $17,821.50 (an extra $3,901.50), and the Medicare levy rises from $1,560.00 to $1,820.10 (an extra $260.10). The extra tax is $4,161.60, and the net payout is $8,843.40 — not “about $9,000”.
Second, there is no flat 30% tax on a long service leave payout. The payout is stacked on top of your other income for the year, and the tax on it depends on that total. If the same employee resigned halfway through the year, with only $39,000 of salary that year, their total taxable income would be $52,005. The extra tax on the payout would then be only $3,261.60, and the net payout $9,743.40 — exactly $900.00 more than the $8,843.40 they would keep if the same payout sat on top of a full $78,000 year.
Example 4: $115,000 salary, 20 years of service — and the South Australia gap
- Weekly pay: $115,000 ÷ 52 = $2,211.54
- Accrued leave (NSW/VIC/QLD/WA/TAS rate): 20 × 0.8667 = 17.33 weeks
- Leave value: 17⅓ weeks × $2,211.54 = $38,333.33
The calculator shows 17.34 weeks and $38,348.08 — $14.75 too high, from its rounded rate. But that is the small error. In South Australia or the Northern Territory, 20 years is worth 26 weeks and $57,500.00. The calculator understates that by $19,151.92.
The tax on a lump sum is substantial at this level. If the $38,348.08 payout is added to a full $115,000 year, taxable income becomes $153,348.08. Income tax rises from $25,020.00 to $37,808.79 (an extra $12,788.79), and the Medicare levy rises from $2,300.00 to $3,066.96 (an extra $766.96). The extra tax is $13,555.75, leaving a net payout of $24,792.33. Part of the payout is taxed at 37%, because the lump sum pushes total income over the $135,000 threshold.
One caution: the page calls this worker a “long-serving public sector employee”, then applies the general private-sector rate. Public-sector long service leave is often under a different scheme — Commonwealth employees, for example, get 13 weeks after 10 years — and the page gives no state and no scheme. Its 17.34 weeks cannot be relied on for a public servant at all.
Example 5: $90,000 salary, 7 years in Victoria — the earliest payout
- Weekly pay: $90,000 ÷ 52 = $1,730.77
- Accrued leave: 7 years is 364 weeks of service; 364 ÷ 60 = 6.07 weeks
- Leave value: (364 ÷ 60) × $1,730.77 = $10,500.00
Victoria and the ACT are the only jurisdictions where 7 years is enough to take leave — and to be paid it out on termination, including on an ordinary resignation. The same 7 years in New South Wales would be worth the same 6.07 weeks and $10,500.00, but only as a pro-rata payout if the job ended for a qualifying reason. In Queensland it would be worth nothing on an ordinary resignation.
What the Calculator Gets Wrong
The long service leave calculator Australia workers use gets its arithmetic right. Its assumptions are wrong. These are the errors the blog guide corrects — the calculator page itself has not been fixed, and that is the site owner’s call, not this guide’s.
- One rate for the whole country — the central error. The calculator applies 0.867 weeks a year everywhere. South Australia and the Northern Territory accrue at 1.3 weeks a year. At 10 years on $80,000, the calculator shows $13,338.46 where the correct figure is $20,000.00 — an understatement of $6,661.54. At 20 years on $115,000, it shows $38,348.08 where the correct figure is $57,500.00 — an understatement of $19,151.92.
- The $78,000 tax example understates the tax and misstates how it works. The page claims “roughly $4,000 in tax, leaving about $9,000 net”. The correct figures on its own facts are $4,161.60 in tax and $8,843.40 net. Worse, the page presents a flat 30% as if the payout were taxed on its own. It is stacked on your income for the year — a mid-year resignation leaves $9,743.40 net.
- A display inconsistency in the default result. The calculator shows the default entitlement as 8.7 weeks, but its dollar value of $13,338.46 is calculated on 8.67 weeks. At 8.7 weeks the value would be $13,384.62.
- Rounding in the accrual rate. The calculator uses 0.867 instead of the exact 0.8667 (8⅔ weeks per 10 years). The overstatement is $5.13 on an $80,000 salary at 10 years and $14.75 on a $115,000 salary at 20 years.
- The 20-year example is framed as a public servant. The page calls the $115,000 worker a “long-serving public sector employee”, then applies the general private-sector rate. Public-sector long service leave is often under a different scheme, and the page gives no state and no scheme.
- Parental leave is oversimplified. The page says approved parental leave “counts as continuous service” in most states. That hides the distinction that matters: unpaid parental leave usually preserves continuity but does not accrue leave in most states, while Victoria counts the first 52 weeks towards accrual.
- The tax guidance is vague to the point of being unusable. “Your employer may withhold PAYG at a flat rate or use the marginal rate depending on the payment type” tells the reader nothing. The ATO’s Schedule 7 sets it exactly — marginal rates on a normal termination, flat 32% on a genuine redundancy.
- No mention that long service leave is not an ETP. A reader who has just read the redundancy guide could assume the same concessional ETP treatment applies. It does not. Unused long service leave is not an employment termination payment, the ETP caps do not apply to it, and it gets no tax-free component.
- No warning about resignation timing. The page says leaving at nine years instead of ten “could mean forfeiting a significant entitlement depending on your state’s pro-rata rules”. It does not say that in Queensland, Tasmania and the Northern Territory an ordinary resignation at nine years forfeits the whole entitlement, while the same resignation in Victoria, Western Australia or South Australia is paid in full.
- Casual entitlements are left vague. The page says several states “have extended entitlements to long-term regular casuals” without saying which states, or that the test is continuity of engagement. In New South Wales, Victoria, Queensland and Tasmania the state Acts expressly cover casual employees — subject to continuity — and that is a fact a casual worker needs, not a hint.
How a Long Service Leave Payout Is Taxed in 2026–27
The tax treatment depends on three things: whether you take the leave or are paid it out, when the leave accrued, and why your employment ended. All figures below use 2026–27 rates unless a year is stated.
The 2026–27 tax brackets
Long service leave taken during employment is taxed as ordinary salary, at your marginal rate. A payout on termination is also added to your taxable income for the year. The resident brackets for 2026–27, verified against the ATO:
| Taxable income | Tax on this income |
|---|---|
| $0 – $18,200 | Nil |
| $18,201 – $45,000 | 15c for each $1 over $18,200 |
| $45,001 – $135,000 | $4,020 plus 30c for each $1 over $45,000 |
| $135,001 – $190,000 | $31,020 plus 37c for each $1 over $135,000 |
| $190,001 and over | $51,370 plus 45c for each $1 over $190,000 |
The only change from 2025–26 is the second bracket: 16% became 15% on 1 July 2026. The 2025–26 figures were $4,288 plus 30c over $45,000, $31,288 plus 37c over $135,000, and $51,638 plus 45c over $190,000. These rates exclude the 2% Medicare levy, which applies on top for most taxpayers above the low-income thresholds.
The one-point cut saves at most $268 a year, and it does not change the tax on any worked example in this guide — the payouts in those examples sit in the 30% or 37% brackets in both years. Tax figures in this guide are before any deductions and before tax offsets.
Withholding on a termination payout — ATO Schedule 7
Withholding is not the same as the final tax. Your employer withholds an amount when the payout is made, and the final tax is worked out when you lodge. The ATO’s Schedule 7 sets the withholding for unused leave paid on termination:
| Leave accrued | Normal termination (resignation, retirement, dismissal) | Genuine redundancy, invalidity or early retirement scheme |
|---|---|---|
| Before 16 August 1978 | 5% of the payment taxed at marginal rates (Lump Sum B) | 5% of the payment taxed at marginal rates (Lump Sum B) |
| 16 August 1978 to 17 August 1993 | Flat 32% (Lump Sum A) | Flat 32% (Lump Sum A) |
| After 17 August 1993 | Marginal rates, included in salary and wages | Flat 32% (Lump Sum A) |
For almost everyone working today, only the last row matters: leave accrued after 17 August 1993 is the whole balance, or nearly all of it. On an ordinary resignation or retirement, it is withheld at your marginal rates and taxed exactly like salary. On a genuine redundancy, it is withheld at a flat 32% and reported as Lump Sum A. If you do not give your employer your Tax File Number, withholding jumps to 47%.
Read more: Income Tax Calculator Australia: Complete Guide to Income Tax, Brackets and Take-Home Pay
What the payout is not
Three distinctions keep people out of trouble. First, an unused long service leave payout is not an employment termination payment. The ETP tax-free limit for genuine redundancy, the $270,000 ETP cap and the 17% rate at age 60 do not apply to it. There is no tax-free component on long service leave, in any circumstances.
Second, it is not taxed at a flat rate on a normal termination. The payout is added to your taxable income, and the rate that applies is the marginal rate on the dollars it occupies — 15%, 30% or 37%, depending on where it lands.
Third, it does count towards your HELP repayment income. A payout that pushes your repayment income over the threshold can trigger or increase a compulsory HELP repayment at assessment. The 2026–27 HELP repayment threshold is $69,528. Withholding under Schedule 7 does not include HELP repayments, so a HELP debtor can face a bill at lodgement even after the withholding looks right.
Taking the leave vs taking the payout
Taking long service leave during employment and taking the money on termination are taxed on the same principles, but the timing changes the result. Taking it as leave means you are paid your ordinary pay each pay period, PAYG is withheld as normal, and superannuation is paid on it. Annual leave keeps accruing while you are on paid long service leave. If the leave spans two financial years, the pay is taxed in the year each part is paid — which can split a large balance across two years’ brackets.
Taking it as a lump sum on termination means the whole balance lands in one year’s taxable income, on top of the salary you earned that year. A large balance can push you into the 37% bracket, as Example 4 shows. On a genuine redundancy the withholding is a flat 32%, which may be more or less than the final tax — the difference is settled at lodgement.
You generally cannot cash it out while you stay employed. If you can choose the timing, run both options through the income tax calculator before deciding — the difference on a $38,000 balance can be thousands.
Part-Time, Casual and Portable Long Service Leave
Part-time employees accrue long service leave on the same basis as full-timers. The weeks are the same; the weekly rate is lower, because it reflects the part-time hours. A part-timer on $45,000 a year accrues 8.67 weeks after 10 years, worth $7,500.00 — the same weeks a full-timer on $80,000 accrues, valued at their own weekly rate of $865.38.
Casual employees are covered by the state Acts in New South Wales, Victoria, Queensland and Tasmania, subject to continuity of engagement. In Victoria, casuals and seasonal employees accrue from day one. In New South Wales, the Act provides for full-time, part-time and casual workers alike.
The test is continuity, not the label. Gaps between engagements can break continuity, and the rules differ by state — so a casual who has worked regularly for the same employer for years should check the continuity rules in their state Act rather than assuming the loading they were paid replaces the entitlement.
Portable schemes are the exception to the one-employer rule. Every state and territory has legislation for portable long service leave in industries where workers change employers often — building and construction, contract cleaning, community services and security, plus a national scheme for coal mining. Under a portable scheme, your entitlement follows you between employers in the same industry, and the scheme — not your employer — holds the balance.
| State / Territory | Building and construction portable scheme |
|---|---|
| Australian Capital Territory | ACT Leave |
| New South Wales | Long Service Corporation |
| Northern Territory | NT Build |
| Queensland | QLeave |
| South Australia | Portable Long Service Leave SA |
| Tasmania | TasBuild |
| Victoria | LeavePlus (formerly CoINVEST) |
| Western Australia | MyLeave |
In Victoria’s construction scheme, workers become eligible to claim after 7 years (1,820 days) of service in the industry, accruing at 1.3 weeks a year. New South Wales added a portable scheme for community services workers from 1 July 2025, with leave available after 7 years in the industry. If you work in one of these industries, check your scheme balance separately — the calculator on this page does not model portable schemes.
Read more: Weekly Pay Calculator Australia: Complete Guide to Weekly Pay, Tax and Take-Home Pay
Parental Leave, Unpaid Leave and Breaks in Service
Continuous service is the foundation of long service leave, and two different questions decide it: does an absence break continuity, and does the absence count towards the accrual period? They are not the same question, and confusing them is a common error.
Paid leave never breaks continuity, and it counts as service. Annual leave, paid personal leave, paid parental leave and long service leave itself all count. Unpaid leave is different. In most states, unpaid parental leave does not break continuity, but it does not count towards the accrual period either. An employee who takes a year of unpaid parental leave will need to work a further year to reach the same milestone.
Victoria is the exception: the first 52 weeks of unpaid parental leave count towards accrual. Absences for illness or injury, including time on workers compensation, do not break continuity in Victoria regardless of length. A transfer of business does not break continuity where the new owner continues the same business and you continue to be employed in it — your service carries over. A genuine break in employment, where you leave and are later re-employed, starts the clock again unless an award, agreement or the Act preserves it.
Superannuation on Long Service Leave
The superannuation guarantee rate is 12% of ordinary time earnings in both 2025–26 and 2026–27. From 1 July 2026, Payday Super applies: contributions must reach your fund within 7 business days of payday. But super is not payable on every part of a long service leave entitlement:
| Long service leave payment | Super payable? |
|---|---|
| Long service leave taken during employment | Yes — it is ordinary time earnings |
| Unused long service leave paid out on termination | No — it is not ordinary time earnings |
That distinction is worth real money. On an $80,000 salary, 8.67 weeks of leave taken during employment attracts about $1,600.00 of super (12% × $13,333.33). The same balance paid out on termination attracts none.
Long Service Leave and Your Final Pay
Long service leave is usually only one part of a final payout. When employment ends, the components stack — and each is taxed and reported differently.
| Final pay component | How it is taxed | Super? |
|---|---|---|
| Unused annual leave (incl. loading) | Schedule 7: marginal rates on normal termination, flat 32% on genuine redundancy (Lump Sum A) | No |
| Unused long service leave | Schedule 7: marginal rates on normal termination, flat 32% on genuine redundancy (Lump Sum A) | No |
| Genuine redundancy pay | Tax-free up to $13,598 + $6,801 per completed year (2026–27); balance is an ETP at 32% under 60, 17% at 60+ | No |
| Payment in lieu of notice | Counts towards the redundancy tax-free limit; excess is an ETP | Yes |
| Normal wages to the last day | Ordinary income at marginal rates | Yes |
Check your final payslip line by line. Long service leave paid out on termination should appear as Lump Sum A if it is on a genuine redundancy (or an older accrual), or in salary and wages if it is a post-17 August 1993 accrual on a normal termination.
If the components are lumped into one line, ask payroll to break them out — a single combined line is where final pays go wrong. A redundancy does not change your long service leave entitlement: on a genuine redundancy it is paid out in full alongside the redundancy payment, once the pro-rata threshold is reached.
Common Mistakes
- Trusting the calculator in South Australia or the Northern Territory. Its single 0.867 rate understates a 10-year entitlement by $6,661.54 on an $80,000 salary. Check your state’s rate first.
- Assuming the rules are the same everywhere. The same 8 years is worth $16,000.00 in South Australia and nothing on an ordinary resignation in Queensland. Your state decides.
- Resigning before the pro-rata threshold. An ordinary resignation at 9 years forfeits the whole entitlement in Queensland, Tasmania and the Northern Territory. Check the table before you hand in your notice.
- Treating the payout as if it were taxed on its own. It stacks on top of your income for the year. A mid-year resignation can leave $900.00 more in your pocket than the same payout on top of a full year’s salary.
- Assuming a payout is tax-free like redundancy pay. Long service leave has no tax-free component and is not an employment termination payment. The ETP rules do not apply to it.
- Entering the full-time salary when you work part-time. The weeks are the same, but the value is not. Enter your actual part-time annual salary.
- Counting unpaid parental leave as service. In most states it preserves continuity but does not accrue leave. Victoria counts the first 52 weeks; other states generally do not.
- Forgetting the super difference. Leave taken during employment attracts 12% super. The same balance paid out on termination attracts none — about $1,600.00 on an $80,000 salary at 10 years.
- Ignoring a portable scheme balance. If you work in construction, cleaning, community services or security, your scheme balance may be larger than your single-employer entitlement — and the calculator cannot see it.
- Not checking the final payslip components. Long service leave, annual leave, redundancy pay and notice are each taxed and reported differently. A payslip that lumps them together hides errors.
Practical Tips
- Run the long service leave calculator Australia workers use twice. Once with your actual figures, and once with your state’s correct rate from the table above, so you can see how far the calculator’s figure is from the right one.
- Check your state before you resign. The pro-rata table in this guide takes a minute to read and can be worth thousands.
- Get your service dates in writing. Ask payroll for your continuous service start date, any breaks, and your accrued balance in weeks — not just dollars.
- Take the leave if you can. It is paid at your ordinary rate, it attracts super, annual leave keeps accruing while you are on it, and it does not land as a single lump sum in one tax year.
- If you must take the payout, mind the year. A payout on top of a full year’s salary is taxed harder than the same payout in a year when you earned less. Model both through the income tax calculator.
- Keep the accrual periods separate. If any of your leave accrued before 18 August 1993, it is taxed differently — ask payroll to split it out on the payslip.
- Check portable scheme balances when you change jobs. In construction and the other portable industries, your entitlement follows you — but only if your service is recorded with the scheme.
- Do not cash out what you cannot cash out. Long service leave must be taken as leave while you are employed. The payout only arises when the employment ends.
Read more: Pro-Rata Salary Calculator Australia: Complete Guide to Part-Time Pay, Tax and Take-Home Salary
How much long service leave do I get after 10 years in Australia?
In most states — New South Wales, Victoria, Queensland, Western Australia and Tasmania — you get 8.67 weeks (about two months) after 10 years of continuous service with the same employer. South Australia and the Northern Territory give 13 weeks. Victoria and the ACT let you take leave after 7 years instead of 10.
How is long service leave calculated?
Divide your annual salary by 52 to get your weekly pay, then multiply your years of service by your state’s accrual rate — 0.8667 weeks a year in most states, 1.3 weeks a year in South Australia and the Northern Territory — and multiply the weeks by your weekly pay. On an $80,000 salary with 10 years in New South Wales, the calculator shows $13,338.46; at the exact statutory rate the figure is $13,333.33.
Can I cash out long service leave when I quit?
If your employment ends after you have reached the pro-rata threshold in your state, your accrued long service leave is paid out as a lump sum in your final pay. The threshold is 5 years in New South Wales and the ACT, and 7 years elsewhere. In New South Wales, Queensland, Tasmania, the ACT and the Northern Territory, a payout before the full qualifying period is only available if the employment ends for a qualifying reason. You generally cannot cash out long service leave while you stay employed.
Is long service leave paid out tax-free?
No. A long service leave payout is taxed as ordinary employment income, and there is no tax-free component — unlike a genuine redundancy payment. On a normal termination, leave accrued after 17 August 1993 is taxed at your marginal rates. On a genuine redundancy it is withheld at a flat 32%. Leave accrued between 16 August 1978 and 17 August 1993 is withheld at 32%, and only 5% of leave accrued before 16 August 1978 is taxable.
Do casual workers get long service leave?
Yes, in several states. The Long Service Leave Acts in New South Wales, Victoria, Queensland and Tasmania expressly cover casual employees, subject to continuity of engagement. In Victoria, casuals and seasonal employees accrue from day one. The test is whether your engagement has been continuous — gaps between engagements can break continuity, and the rules differ by state.
Does long service leave accrue during parental leave?
Paid parental leave counts as service and accrues long service leave. Unpaid parental leave is different: in most states it does not break continuity, but it does not count towards accrual either. Victoria is the exception — the first 52 weeks of unpaid parental leave count towards accrual.
What is the difference between long service leave and annual leave?
Annual leave is a National Employment Standards entitlement: 4 weeks a year from your first day, accessible at any time, and paid out in full whenever employment ends. Long service leave is set by state law, accrues over years rather than months, and is generally only available after 7 to 10 years of continuous service with the same employer. Annual leave is paid at your base rate plus loading where it applies; long service leave is paid at your ordinary rate of pay.
Can I take long service leave before 10 years?
In Victoria and the ACT, yes — you can take leave after 7 years of continuous service. In the other states you generally must wait 10 years to take leave, although a pro-rata payout may be available if your employment ends after 5 years (New South Wales and the ACT) or 7 years (the other states), subject to the reason it ended.
Is superannuation paid on long service leave?
Yes, when you take it as leave — long service leave taken during employment is ordinary time earnings, so the 12% superannuation guarantee applies. No, when it is paid out on termination — an unused long service leave payout is not ordinary time earnings, so no super is payable on it. On an $80,000 salary, taking 8.67 weeks as leave rather than a payout is worth about $1,600.00 in super.
What happens to my long service leave if I am made redundant?
Your accrued long service leave is paid out in full alongside your redundancy payment, once you have reached the pro-rata threshold in your state — 5 years in New South Wales, 7 years elsewhere. It is taxed separately from the redundancy payment: the redundancy component may be partly tax-free, but the long service leave component is not an employment termination payment and has no tax-free component. On a genuine redundancy it is withheld at a flat 32%.
Final Takeaway
Long service leave is the most valuable leave entitlement most Australians will ever accrue — and the easiest to undervalue, because the rules change at every state border. The long service leave calculator Australia workers use on this page gets the arithmetic right, but it runs on one accrual rate for the whole country. In South Australia and the Northern Territory that rate is wrong by a third, and its tax example understates the tax by treating the payout as if it were taxed on its own.
Weekly pay = annual salary ÷ 52
Accrued weeks = years of service × your state’s accrual rate (0.8667 a year in NSW, VIC, QLD, WA, TAS and the ACT; 1.3 a year in SA and the NT)
Leave value = accrued weeks × weekly pay
Tax on a payout: post-17 August 1993 accruals are taxed at marginal rates on a normal termination, or withheld at a flat 32% on a genuine redundancy — no tax-free component, and the payout is not an ETP
Check your weeks against your state’s rate, check your pro-rata position before you resign, and check your final payslip line by line — long service leave, annual leave, redundancy pay and notice are each taxed differently, and the payslip is where the errors hide. If you work in South Australia or the Northern Territory, do not rely on the calculator’s figure at all: your entitlement is 13 weeks at 10 years, and it is worth 50% more than the calculator shows.