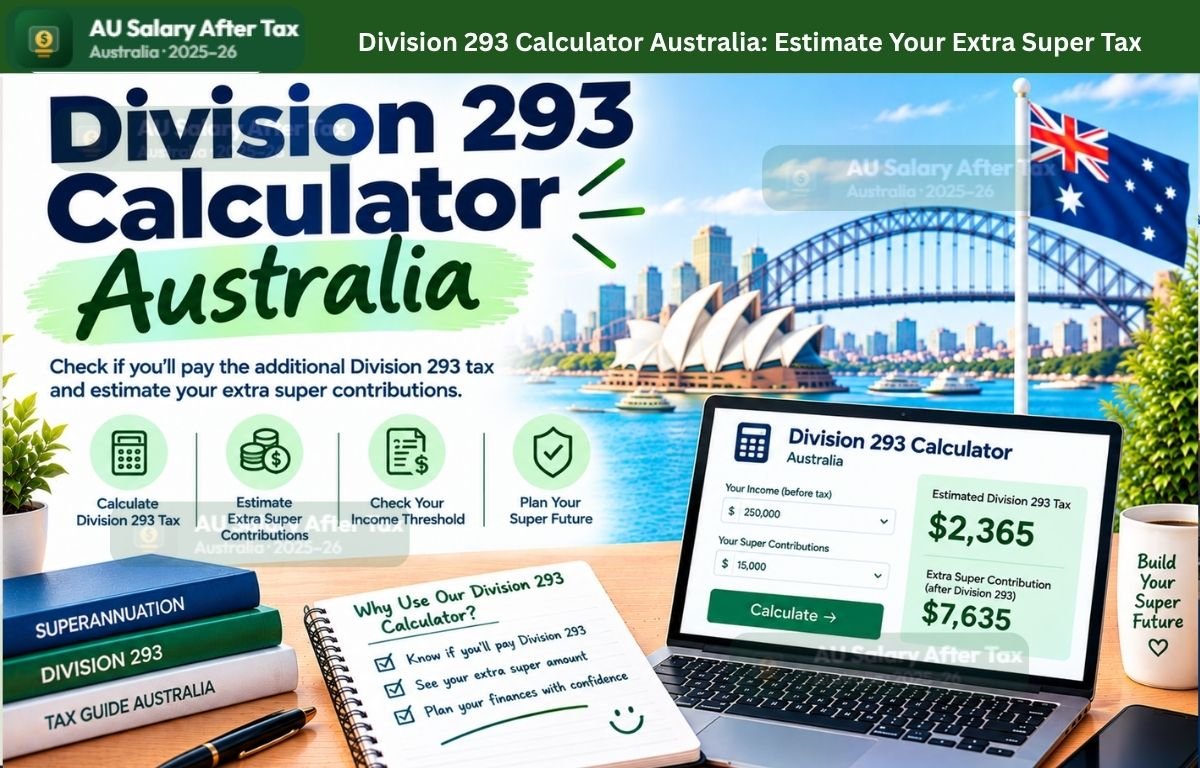
Super contributions are taxed at 15% inside your fund — a great deal when your marginal rate is 47%. Division 293 exists to claw some of that deal back from very high earners: an extra 15% tax when your income plus concessional contributions tops $250,000. The Division 293 Calculator Australia tells you in seconds whether you’re caught and how much extra tax you’ll owe.
The calculator’s maths checks out — I verified it on multiple samples. But the guide text on the same page contains several factual errors, including a worked example that uses the wrong tax bracket and an outdated Medicare surcharge threshold. This guide gives you the correct figures: how Division 293 really works, five worked examples with verified maths, what counts toward the $250,000 threshold, how it interacts with salary sacrifice and the $30,000 cap, and how to pay the bill.
Table of Contents
Important: Figures use 2025–26 Australian tax and super rules. This is general information, not personal financial advice. Division 293 interacts with your full tax position; consider licensed advice for large amounts.
What Is the Division 293 Calculator Australia?
Division 293 is an additional 15% tax on concessional super contributions — on top of the standard 15% contributions tax your fund already pays. It applies when your “income for Division 293 purposes” plus your concessional contributions exceeds $250,000. The extra tax falls on the lesser of your total concessional contributions and the amount by which you’re over $250,000.
The calculator answers the practical question: “am I over the threshold, and if so, what’s my Division 293 bill?” It takes your taxable income and concessional contributions, works out the excess, and applies the 15%.
Who should use it:
- Anyone earning near or above $250,000 (including super)
- Salary-sacrificers checking whether extra contributions trigger the tax
- People who received a Division 293 assessment and want to check the ATO’s maths
- High earners comparing salary sacrifice vs personal deductible contributions
Important: The calculator’s estimate uses just two inputs — taxable income and concessional contributions. The ATO’s real calculation also adds fringe benefits, investment losses and other adjustments (listed below), so treat the result as a close estimate, not the final assessment.
What Does the Division 293 Calculator Do?
The Division 293 Calculator Australia keeps it simple — two inputs in, a full breakdown out.
| Input | What to enter |
|---|---|
| Taxable Income | Your taxable income for the year (default $220,000) |
| Concessional Super Contributions | Total concessional: SG + salary sacrifice + deductible personal (default $27,500) |
| Output | What it means |
|---|---|
| Division 293 Tax (hero) | The extra 15% tax you owe — $0 if you’re under the threshold |
| Income for Div 293 Purposes | Taxable income + concessional contributions |
| Division 293 Threshold | $250,000 (fixed, not indexed) |
| Amount Over Threshold | How far your combined figure exceeds $250,000 |
| Div 293 Taxable Amount | The lesser of concessional contributions and the excess |
| Status | “Division 293 applies” or “Below threshold — no extra tax” |
How to Use the Division 293 Calculator
Step 1 — Enter your taxable income. Your expected taxable income for the year (after deductions). Don’t subtract super — the calculator adds contributions separately.
Step 2 — Enter total concessional contributions. SG + salary sacrifice + any personal deductible contributions for the year.
Step 3 — Read the “Div 293 Taxable Amount” line. That’s the figure the 15% applies to. If it equals your full concessional contributions, you’re well over the threshold; if it equals the excess, you’re just over the line.
The calculator’s formula is exactly the ATO’s: taxable amount = the lesser of concessional contributions and (income for Div 293 purposes − $250,000), then 15% on that amount.
How Division 293 Tax Works — the Extra 15%
The policy logic is simple: super’s 15% tax rate is a concession worth 32 cents per dollar to someone on the top marginal rate (47%). Division 293 halves that concession for very high earners by adding another 15% — taking the total tax on affected contributions to 30%.
The mechanics:
Div 293 taxable amount = lesser of (concessional contributions, income for Div 293 purposes − $250,000)
Division 293 tax = 15% × Div 293 taxable amount
Three things to notice:
- It’s the lesser of the two figures. Just over the threshold? Only the small excess is taxed extra. Well over? All your concessional contributions cop the extra 15%.
- The 15% is on top of the 15% your fund already paid. Affected contributions face 30% total — still better than 47% marginal, but much less generous than 15%.
- The tax is levied on you personally, via a notice of assessment after you lodge your tax return — not on the fund. You can pay from your own pocket or elect to release money from super.
Read more: Best Income Tax Calculator Australia 2025–26: Complete Guide
Worked Examples
All figures verified against the ATO formula. Each example shows what the calculator displays.
Example 1 — $240,000 taxable income, $30,000 concessional (the classic breach)
| Figure | |
|---|---|
| Taxable income | $240,000 |
| Concessional contributions | $30,000 |
| Income for Div 293 purposes | $270,000 |
| Amount over threshold | $20,000 |
| Div 293 taxable amount | $20,000 (lesser of $30,000 and $20,000) |
| Division 293 tax (15%) | $3,000 |
The calculator shows exactly $3,000.00 with status “Division 293 applies” — verified correct.
Example 2 — $260,000 taxable income, $20,000 concessional
| Figure | |
|---|---|
| Taxable income | $260,000 |
| Concessional contributions | $20,000 |
| Income for Div 293 purposes | $280,000 |
| Amount over threshold | $30,000 |
| Div 293 taxable amount | $20,000 (lesser of $20,000 and $30,000) |
| Division 293 tax (15%) | $3,000 |
Same $3,000 bill, different shape: here the full concessional amount is caught because the excess ($30,000) exceeds contributions. The calculator shows $3,000.00 — verified correct.
Example 3 — $230,000 salary with full SG (no salary sacrifice)
| Figure | |
|---|---|
| Taxable income | $230,000 |
| Concessional (12% SG: $230,000 × 12%) | $27,600 |
| Income for Div 293 purposes | $257,600 |
| Amount over threshold | $7,600 |
| Div 293 taxable amount | $7,600 |
| Division 293 tax (15%) | $1,140 |
You don’t need a $250,000 salary to be caught — $230,000 of salary plus SG is enough. The calculator page’s own worked example gives $1,140, and the maths checks out.
Example 4 — $200,000 salary, $5,000 sacrificed (below the line)
| Figure | |
|---|---|
| Taxable income ($200,000 − $5,000) | $195,000 |
| Concessional (SG $24,000 + $5,000 sacrifice) | $29,000 |
| Income for Div 293 purposes | $224,000 |
| Amount over threshold | $0 |
| Division 293 tax (15%) | $0 |
No Division 293 here — and the $29,000 stays within the $30,000 concessional cap. This is the comfort zone: high earner, sensible sacrifice, no extra tax.
Example 5 — the ATO’s own example (Jan)
The ATO publishes this exact scenario: Jan’s Division 293 income is $240,000 and Division 293 super contributions are $15,000 — total $255,000. The taxable amount is the lesser of $15,000 and the $5,000 excess = $5,000. Division 293 tax = 15% × $5,000 = $750.
What Counts Toward the $250,000 Threshold
The calculator simplifies this to taxable income + concessional contributions. The ATO’s actual “Division 293 income” starts from the Medicare levy surcharge income calculation (disregarding reportable super) and includes:
| Added | Subtracted |
|---|---|
| Taxable income | Super lump sum taxed elements (zero rate) |
| Total reportable fringe benefits | Assessable First Home Super Saver released amount |
| Net financial investment loss | |
| Net rental property loss | |
| Family trust distribution tax amounts |
Then concessional super contributions are added on top to test against $250,000. Two consequences:
- Fringe benefits count. A $230,000 salary with $25,000 of reportable fringe benefits is over the line before super is even added. The calculator has no fringe-benefits input — add them to your thinking manually.
- Losses are added back. Negatively geared investment losses don’t shelter you from Division 293 the way they cut taxable income.
What the Calculator’s Guide Gets Wrong
The calculator’s arithmetic is correct, but its guide text has four factual problems:
1. Wrong tax bracket in the salary-sacrifice example. The page claims “$10,000 sacrificed on a $280,000 income saves roughly 39% marginal tax (37% + 2% Medicare)… a net benefit of around 9%.” But $280,000 sits in the 45% tax bracket, not 37% — the marginal rate is 45% + 2% = 47%. Correct maths with full Division 293: 47% − 15% − 15% = 17% net benefit ($1,700 per $10,000), not 9%. Without Division 293: 47% − 15% = 32% ($3,200), not the page’s 24%.
2. Outdated Medicare levy surcharge threshold. The page says the surcharge applies “if you earn above $93,000 single” — that’s the 2022–23 figure. For 2025–26 the Tier 1 threshold is $101,000 for singles ($202,000 for families).
3. Misleading carry-forward claim. The page says the cap is “$30,000 for 2025–26 for most people, or $36,000 if you have unused cap space.” Carry-forward doesn’t create a flat $36,000 cap — it lets you use your actual unused amounts from up to five prior years (which could be far more, or less, than $6,000 extra). And per the ATO, contributions under an increased carry-forward cap still count fully for Division 293.
4. Threshold history. The page says $250,000 “has remained… since the measure was introduced.” Division 293 started in 2012–13 with a $300,000 threshold; it was lowered to $250,000 from 1 July 2017. The $250,000 figure has been frozen since — it’s not indexed.
None of these break the calculator itself, but they’re the kind of details that lead to bad planning if taken at face value.
Division 293 and the $30,000 Cap
Division 293 and the concessional contributions cap are separate taxes that often arrive together:
| Division 293 | Excess concessional contributions | |
|---|---|---|
| Trigger | Income + concessional > $250,000 | |
| Rate | Extra 15% | Marginal rate (less 15% offset) + interest |
| What’s taxed | Lesser of excess/concessional | The excess amount |
Key interactions:
- Excess concessional contributions are excluded from Division 293. The ATO disregards them in the Div 293 calculation — you don’t pay both taxes on the same dollar.
- Going over the cap doesn’t change your Division 293. The excess is ignored for Div 293 purposes entirely — both in the $250,000 threshold test and in the taxable amount — though it faces excess-contributions tax separately.
- Salary sacrifice near the threshold needs both checks. Size the sacrifice so concessional stays ≤ $30,000 and model the Div 293 cost.
Salary Sacrifice Near the Threshold — Strategy
Here’s the subtlety most articles miss: whether extra salary sacrifice increases your Division 293 bill depends on how far over the threshold you are.
Well over the line (excess bigger than contributions): every extra sacrificed dollar attracts the full extra 15%. At the 47% top marginal rate, the net benefit per sacrificed dollar is 47% − 15% − 15% = 17%. Still positive — $1,700 per $10,000 — but a long way from the 32% you’d get without Division 293.
Just over the line (excess smaller than contributions): the Div 293 taxable amount is capped by the excess, so additional sacrifice may barely move the Division 293 bill at all — the net benefit stays near 32%. (Example 1 above: at $270,000 Div 293 income with $30,000 concessional, the bill is driven by the $20,000 excess.)
Practical rules:
- Model before you sacrifice — run the Division 293 calculator with and without the planned sacrifice.
- Don’t sacrifice just to dodge Division 293 — sacrificed amounts are added back to Div 293 income, so it rarely helps you slip under.
- Consider timing — if a one-off event (bonus, capital gain) pushes you over for a single year, Division 293 may be a one-year cost; size that year’s contributions accordingly.
- Non-concessional contributions don’t attract Division 293 (no deduction, but no extra tax either).
Read more: Salary Sacrifice Calculator Australia: Complete Guide to Salary Sacrifice, Super and Tax Savings
Paying the Tax — From Your Pocket or Your Super
The ATO issues a Division 293 notice of assessment after you lodge your tax return (once your fund has reported contributions — so it can arrive months after your regular assessment). Then you choose:
- Pay personally — from your own money by the due date on the notice. Preserves your super balance; needs cash flow. Pay on time to avoid interest.
- Release from super — you have 60 days from the date of the notice to elect a release via the release authority that comes with it. Reduces retirement savings; no out-of-pocket cost.
There’s no universally right answer — it depends on your liquidity and how you value the super balance. One warning: if you’re in a defined benefit fund, the tax may be deferred until a benefit is paid, with interest accruing on the deferred debt each year — check the ATO’s defined-benefit rules if that applies to you.
Read more: Tax Refund Estimator Australia: Complete Guide to Tax Refunds, PAYG Withholding and Your Tax Return
Who Gets Caught Most Often
- Senior employees on $230,000–$260,000 — SG alone can push them over; they often don’t realise they’re affected until the assessment arrives.
- Aggressive salary-sacrificers near the threshold — each extra dollar of concessional contributions is added to Div 293 income, so sacrificing toward the threshold can tip you over it.
- People with fringe benefits — reportable fringe benefits count toward the $250,000 test, catching some whose salary looks safe.
- One-off high-income years — a big bonus, redundancy payout or capital gain can trigger Division 293 for a single year.
- Defined benefit members — notional contributions count, and the tax is deferred with interest rather than avoided.
Common Mistakes
- Checking only salary against $250,000 — super contributions (and fringe benefits) are added; $230,000 salary + SG is already over.
- Thinking Division 293 replaces the 15% contributions tax — both apply; affected contributions face 30% total.
- Assuming the threshold is indexed — it’s been frozen at $250,000 since 2017.
- Believing salary sacrifice avoids it — sacrificed amounts are added back to Div 293 income.
- Forgetting the $30,000 cap at the same time — the two taxes are separate; check both.
- Ignoring the assessment — it arrives after your tax return; interest accrues if you don’t pay or elect release by the due date.
- Using the page’s 9% figure — the correct net benefit at $280,000 with full Division 293 is 17%, not 9%.
- Counting on the old $93,000 surcharge threshold — it’s $101,000 for singles in 2025–26.
- Thinking spouse contribution splitting avoids Division 293 — contributions count in the year they’re made; splitting is just a rollover to your spouse’s account and doesn’t reduce your Division 293 bill.
Practical Tips
- Run the calculator before June 30 — there’s still time to adjust contributions for the current year.
- Know your Div 293 income, not just your salary — add SG, salary sacrifice, fringe benefits and investment losses back.
- Keep concessional contributions ≤ $30,000 — breaches add excess-contributions tax on top of Division 293 complexity.
- If well over the threshold, sacrifice anyway — 17% net per dollar at the top rate is still free money.
- If just over the line, model the marginal cost — extra sacrifice may barely move the Div 293 bill.
- Choose your payment method deliberately — pay personally to preserve super, release from super to preserve cash flow.
What is the Division 293 threshold for 2025–26?
$250,000 of income for Division 293 purposes plus concessional contributions. It hasn’t changed since 1 July 2017 (it was $300,000 when introduced in 2012) and it isn’t indexed.
Is Division 293 tax the same as the 15% super contributions tax?
No. The 15% contributions tax is paid by your fund on all concessional contributions. Division 293 is an additional 15% levied on you personally when you’re over the threshold — affected contributions face 30% total.
Does employer super guarantee count toward Division 293?
Yes. All concessional contributions count: 12% SG, salary sacrifice, and personal deductible contributions. SG is added to your income when testing the $250,000 threshold, which is why $230,000 salaries can be caught.
Can I avoid Division 293 by salary sacrificing less?
Reducing salary sacrifice lowers your concessional contributions, which can bring you under the threshold — but you lose the sacrifice tax benefit on that amount. If you’re well over the line, the extra 15% applies to the full concessional amount regardless. Model both scenarios first.
When do I pay Division 293 tax?
The ATO assesses it after you lodge your tax return (once your fund reports contributions). You get a notice of assessment and can pay from personal funds or elect a super release — pay by the due date to avoid interest.
Does Division 293 apply to non-concessional super contributions?
No — only concessional contributions. Non-concessional (after-tax) contributions don’t get a deduction and don’t attract Division 293, though they have their own $120,000 annual cap ($360,000 bring-forward).
Does Division 293 apply if my salary is under $250,000?
Yes, if super pushes the total over. A $230,000 salary with $27,600 SG gives $257,600 for Div 293 purposes — $7,600 over, taxed an extra $1,140. Salary alone isn’t the test.
What if I breach the $30,000 cap and Division 293 in the same year?
Both can apply, but not on the same dollars: excess concessional contributions are excluded from the Division 293 calculation. The excess faces excess-contributions tax at your marginal rate (less a 15% offset) plus interest.
Can Division 293 be released from my super?
Yes — you can elect to have the liability released from your super fund via a release authority instead of paying personally. Defined benefit members have special deferral rules: the tax is deferred (with annual interest) until a benefit is paid.
Has the threshold always been $250,000?
No. Division 293 started in 2012–13 with a $300,000 threshold; it was cut to $250,000 from 1 July 2017 and hasn’t moved since. Don’t assume it will rise with inflation — it isn’t indexed.
Final Takeaway
One formula decides everything:
Division 293 tax = 15% × lesser of (concessional contributions, income for Div 293 purposes − $250,000)
Run your numbers through the Division 293 Calculator Australia — its maths is sound — but read the guide text with the corrections above in mind. Know your full Div 293 income (not just salary), watch the $30,000 cap alongside it, and decide before June 30 whether this year’s contributions need trimming.