There’s a special kind of disappointment in watching a $10,000 bonus land as $6,800. Bonuses feel like gifts — until the tax system treats them exactly like salary. In Australia there is no separate “bonus tax.” Your bonus is ordinary income, taxed at your marginal rate, plus the 2% Medicare levy, plus HELP repayments if you have a study debt. What makes bonuses sting is that the whole amount typically lands in your top tax bracket at once.
This guide explains how bonus tax really works: the marginal-rate calculation the calculator uses, how your employer withholds PAYG on bonuses (including the ATO’s lump-sum formula), what super guarantee applies, how bonuses interact with HELP and the Medicare levy, and the timing and salary-sacrifice rules that can legally shrink the bill.
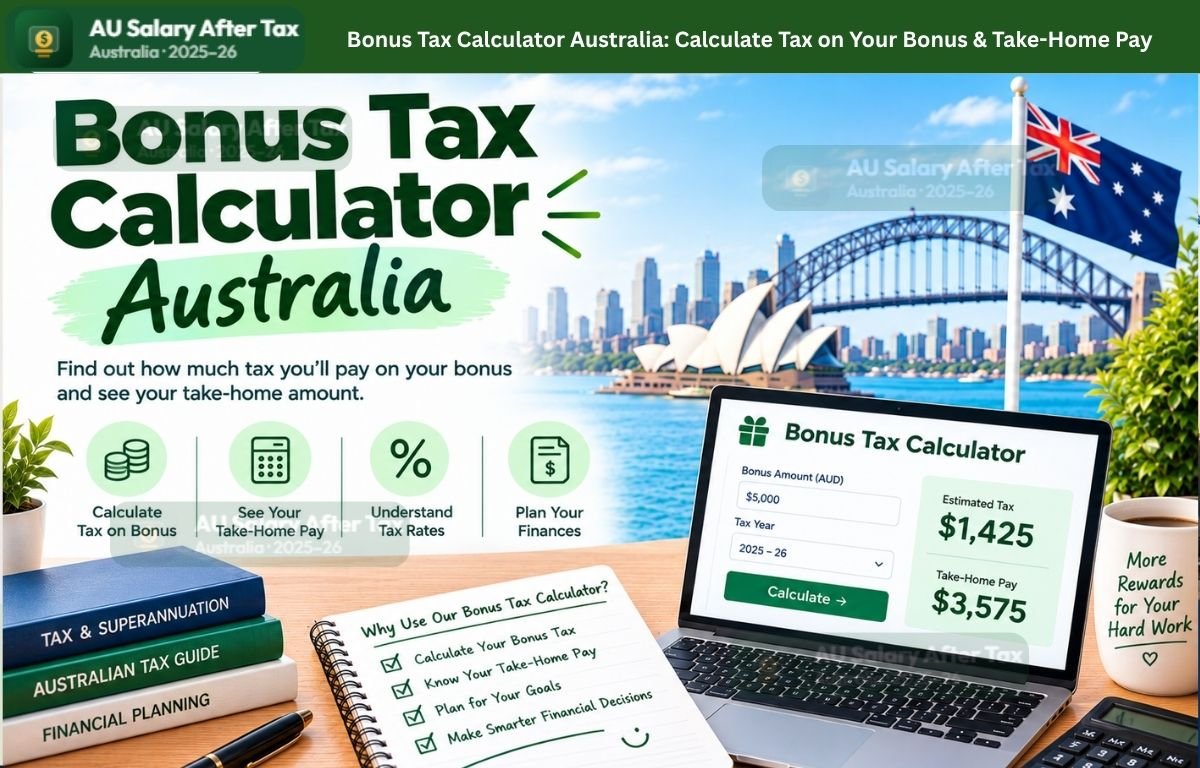
Our Bonus Tax Calculator Australia takes your annual salary and bonus amount and instantly shows the tax on the bonus, your bonus after tax, and the effective rate. This guide shows you how that figure is built — and what the calculator leaves out.
Table of Contents
Important
Figures in this guide use current 2026–27 Australian tax law as the main reference (the financial year we’re in), with 2025–26 figures alongside. The calculator on this site currently uses 2025–26 rates. This guide is general information, not tax or financial advice.
What Is the Bonus Tax Calculator?
The Bonus Tax Calculator Australia is a free online tool that estimates how much of your work bonus you’ll actually keep. Enter your annual salary and bonus amount, toggle whether you have a HECS/HELP debt, and it instantly returns the tax attributable to the bonus, your bonus after tax, the effective bonus tax rate, and the marginal rate applied.
Unlike a full take-home pay calculator, which shows your whole year’s position, this calculator isolates the incremental tax on the bonus itself — the answer to “what does this bonus really cost me in tax?”
Who should use it
- Employees about to receive a performance, annual or project bonus
- Sales professionals on commission-style or quarterly bonuses
- Executives weighing STI/LTI payouts or sign-on bonuses
- Anyone negotiating between a bonus and a salary increase
- Workers with HELP debt checking how a bonus changes repayments
- Finance teams explaining bonus payslips to staff
What Does the Bonus Tax Calculator Do?
Three inputs, six outputs:
| Input | Meaning | What to enter |
|---|---|---|
| Annual Salary | Your base annual gross salary, excluding the bonus | Your salary before the bonus is added |
| Bonus Amount | The gross bonus for the year | The pre-tax bonus figure |
| HECS/HELP debt | Checkbox: do you have a study/training loan debt? | Tick if you have a HELP, VSL or TSL debt |
| Output | Meaning |
|---|---|
| Bonus After Tax (hero) | The bonus left after the incremental tax |
| Annual Salary | Your salary input, echoed back |
| Bonus Amount | Your bonus input, echoed back |
| Tax on Bonus | Income tax + Medicare levy (+ HELP if toggled) on the bonus |
| Bonus After Tax | Same as the hero figure |
| Effective Bonus Tax Rate | Tax on bonus ÷ bonus amount |
| Marginal Rate on Bonus | Your top marginal rate including Medicare (and HELP if toggled) |
How to Use the Bonus Tax Calculator
Step 1: Enter your salary and bonus
Type your annual base salary excluding the bonus — not your total package. Then enter the gross bonus amount. Tick the HECS/HELP box only if you have an outstanding study or training support loan.
Step 2: Review your results
The calculator compares total tax on your salary alone with total tax on salary plus bonus — the difference is the tax on the bonus. Use the effective rate for budgeting (what percentage you actually lose) and the marginal rate to understand which bracket the bonus fell into.
Read more: How to Calculate Your Take-Home Pay in Australia: Salary, Tax and Deductions Explained
How Bonus Tax Is Calculated — the Marginal-Rate Method
There is no bonus tax rate. The calculator uses the marginal-rate method:
Tax on bonus = Tax(salary + bonus) − Tax(salary)
…where “Tax” means income tax plus the 2% Medicare levy (plus the incremental HELP repayment when the HECS box is ticked). Because the bonus sits on top of your salary, nearly all of it is taxed at your top marginal rate — which is why a bonus feels more heavily taxed than the same dollars spread across your salary.
2026–27 resident tax brackets (current year)
| Taxable income | Tax on this income |
|---|---|
| $0 – $18,200 | Nil |
| $18,201 – $45,000 | 15c for each $1 over $18,200 |
| $45,001 – $135,000 | $4,020 + 30c for each $1 over $45,000 |
| $135,001 – $190,000 | $31,020 + 37c for each $1 over $135,000 |
| $190,001 and over | $51,370 + 45c for each $1 over $190,000 |
(The 15% rate on the $18,201–$45,000 bracket started 1 July 2026; it’s legislated to fall to 14% from 1 July 2027.)
2025–26 brackets (what the calculator uses)
Identical thresholds, but 16c (not 15c) on $18,201–$45,000 — a $4,288 base instead of $4,020. The 30%, 37% and 45% brackets are unchanged, so any bonus falling entirely above $45,000 gives the same answer under either year.
Example — $80,000 salary + $10,000 bonus (2026–27, no HELP)
Example Calculation Income tax on $80,000 ($4,020 + 30% × $35,000) $14,520.00 Income tax on $90,000 ($4,020 + 30% × $45,000) $17,520.00 Incremental income tax on bonus $3,000.00 Medicare levy on bonus (2% × $10,000) $200.00 Tax on bonus $3,200.00 Bonus after tax $6,800.00 Effective bonus tax rate 32.0% This matches the calculator’s default result exactly — 30% income tax plus 2% Medicare, because the whole bonus sits in the 30% bracket.
More Worked Examples
Example — $80,000 salary + $10,000 bonus, with HELP debt (2026–27)
Example Calculation Income tax + Medicare on bonus $3,200.00 HELP at $80,000: 15% × ($80,000 − $69,528) $1,570.80 HELP at $90,000: 15% × ($90,000 − $69,528) $3,070.80 Incremental HELP on bonus $1,500.00 Tax on bonus $4,700.00 Bonus after tax $5,300.00 Effective bonus tax rate 47.0% The HELP toggle is the single biggest swing factor: the same bonus keeps $6,800 without a study debt and $5,300 with one.
Example — $50,000 salary + $5,000 bonus (2026–27, no HELP)
Example Calculation Incremental income tax (30% × $5,000) $1,500.00 Medicare levy (2% × $5,000) $100.00 Tax on bonus $1,600.00 Bonus after tax $3,400.00 Effective bonus tax rate 32.0%
Example — bracket push: $130,000 salary + $10,000 bonus (2026–27, no HELP)
Example Calculation Tax on $130,000 ($4,020 + 30% × $85,000) $29,520.00 Tax on $140,000 ($31,020 + 37% × $5,000) $32,870.00 Incremental income tax $3,350.00 Medicare levy (2% × $10,000) $200.00 Tax on bonus $3,550.00 Bonus after tax $6,450.00 Effective bonus tax rate 35.5% The first $5,000 of the bonus is taxed at 32% (30% + 2%); the $5,000 above $135,000 at 39% (37% + 2%). This is the “bracket push” — only the dollars above the threshold pay the higher rate.
PAYG Withholding on Bonuses — What Hits Your Payslip
The calculator shows your annual liability. What actually lands in your bank account on bonus day is decided by PAYG withholding, and the ATO has specific rules for it — Schedule 5, the tax table for back payments, commissions, bonuses and similar payments (NAT 3348).
If the bonus relates to work over more than one pay period (the usual annual bonus), the employer uses Method A:
- Work out withholding on one period’s normal pay.
- Divide the bonus by the number of pay periods it relates to (drop cents) and add it to normal pay.
- Work out withholding on that combined figure.
- Subtract step 1, then multiply by the number of pay periods — that’s the withholding on the bonus.
If the bonus relates to a single pay period, Schedule 5 doesn’t apply — the bonus is just added to that period’s pay and taxed through the normal tables (which can look dramatic on one payslip).
Two things worth knowing: the withholding tables already include the 2% Medicare levy, and if you’ve declared a HELP debt, the employer withholds the extra study-loan (STSL) component from the bonus using the same method.
Example — withholding vs liability ($80,000 monthly salary + $10,000 annual bonus, 2026–27)
Example Calculation Withholding via Schedule 5 Method A (approx.) $3,199.00 True extra annual liability (30% + 2%) $3,200.00 Method A lands within cents of the real liability — by design. But methods differ between employers, and any gap is settled at tax time: over-withholding comes back as a refund, under-withholding becomes a bill.
This is also why bonuses feel over-taxed: a lump sum annualised across pay periods can look alarming on the payslip, and the “flat 32% bonus tax” myth comes from people annualising one heavy pay period in their heads. Your actual rate is always your marginal rate, reconciled in July.
Read more: Australian Pay Calculator: Complete Guide to Salary, Tax and Take-Home Pay
Super Guarantee on Bonuses — the Extra 12% You Don’t See
Your bonus doesn’t just cost tax — it usually earns super. From 1 July 2025 the super guarantee (SG) rate is 12% of ordinary time earnings, and the ATO treats most bonuses as ordinary time earnings (SGR 2009/2): performance bonuses, Christmas bonuses, sign-on bonuses and referral bonuses all attract SG. The only exception is a bonus paid solely for work performed entirely outside ordinary hours.
On a $10,000 annual performance bonus, your employer must pay $1,200 SG on top — money you never see on the payslip but which forms part of your total package. Two caps matter:
| 2025–26 | 2026–27 | |
|---|---|---|
| SG rate | 12% | 12% |
| Maximum contribution base | $62,500 per quarter | $270,830 per year |
| Concessional contributions cap | $30,000 | $32,500 |
From 1 July 2026, Payday Super also applies: SG is calculated each payday and must generally reach your fund within 7 business days (previously it could wait until quarter-end). The maximum contribution base moved to an annual $270,830 figure alongside it.
(ATO – Super guarantee rates and thresholds)
Important
SG is an employer cost — it doesn’t reduce your bonus after tax. But it does count toward your concessional contributions cap, which matters if you’re salary-sacrificing a bonus (see below).
How a Bonus Interacts with HELP, Medicare and the Surcharge
| Item | Does the bonus count? | Detail |
|---|---|---|
| HELP repayment income | Yes | A cash bonus is salary/wages, so it lifts your repayment income — potentially over the $69,528 threshold (2026–27) or into a higher marginal repayment band. The calculator’s HECS toggle models this. |
| Medicare levy (2%) | Yes | The levy applies to total taxable income including the bonus; the calculator includes it. |
| Medicare levy surcharge | Yes | The bonus forms part of income for surcharge purposes — a large bonus can tip you over a surcharge threshold if you lack appropriate hospital cover. The calculator doesn’t model this. |
| Income tax offsets | Partially | The calculator doesn’t model offsets (e.g. low-income tax offset), which can slightly change the real answer at lower incomes. |
Note the calculator’s HECS toggle uses the pre-July-2025 repayment brackets (1%–10% on total income). Under current marginal law the incremental HELP on a bonus is simply 15c or 17c per bonus dollar above the relevant threshold — at $80,000 + $10,000 that’s $1,500, as shown in the worked example above.
What the Calculator Doesn’t Model
The calculator answers one question well — the annual incremental tax on the bonus. It deliberately doesn’t cover:
- Withholding vs liability. It shows the end-of-year marginal-rate liability, not what Schedule 5 puts on your actual bonus payslip (usually within cents, but not identical).
- Medicare levy surcharge for high earners without hospital cover.
- Tax offsets such as the low-income tax offset.
- Multiple bonuses across the year (each one is annualised separately for withholding).
- Salary sacrifice of the bonus into super.
- Division 293 additional tax where income plus concessional super exceeds $250,000.
- Super guarantee timing and the maximum contribution base.
Timing — Which Financial Year Is Your Bonus Taxed In?
Employees are taxed on a receipts basis: a bonus is assessable when it’s paid, not when it’s earned. A bonus for work done in June but paid in July is taxed in the July financial year.
This matters at the margins. A December bonus and a July bonus fall in different tax years — which can mean different brackets, different HELP thresholds, and different marginal rates on the bonus. If you can influence timing (for example, a director choosing when to declare a bonus), the year boundary is the lever. For everyone else, just know which year’s figures your bonus will be assessed under.
Salary-Sacrificing a Bonus into Super
Yes — you can salary-sacrifice a bonus into super, but only if the arrangement is in place before you earn the entitlement. The agreement (ideally in writing) must exist before the performance period ends or the bonus is declared. You cannot retrospectively sacrifice a bonus that’s already been earned — that’s taxed as ordinary salary, full stop.
Why do it? Super contributions are taxed at 15% instead of your marginal rate. On a $10,000 bonus for someone in the 30% bracket (+ 2% Medicare), sacrificing the bonus into super saves roughly $1,700 in tax — at the cost of locking the money away until preservation age. Three catches:
- It counts toward your concessional contributions cap ($30,000 in 2025–26; $32,500 in 2026–27) — breach it and extra tax applies.
- Salary-sacrificed super is a reportable super contribution, which feeds back into your HELP repayment income and the Medicare levy surcharge income test.
- If you’re near the Division 293 threshold ($250,000 income + concessional super), an extra 15% tax can apply to some contributions.
Cash Bonuses vs Other Payments
- A cash bonus is salary/wages — PAYG withholding, not a fringe benefit, and not a “reportable fringe benefit” on your income statement.
- Non-cash rewards (gift cards, holidays, goods) can be fringe benefits — the employer may pay FBT instead of withholding PAYG from you (a minor-benefit exemption under $300 exists for infrequent benefits, with strict conditions).
- A sign-on bonus for a new employee is ordinary salary income when received — not an employment termination payment.
- A “golden handshake” gratuity on termination is generally an employment termination payment (ETP): concessionally taxed within caps ($260,000 in 2025–26; $270,000 in 2026–27, with a $180,000 whole-of-income cap), and taxed at 45% + 2% Medicare above the caps.
Bonus vs Salary Increase — Which Is Better?
A dollar of bonus and a dollar of salary are taxed identically in the same financial year — both are ordinary income at your marginal rate. The differences are structural:
- A salary increase compounds: next year’s rise builds on a higher base; a bonus doesn’t automatically repeat.
- Salary increases typically attract super and leave accruals on the full amount; a one-off bonus may not accrue leave.
- A bonus is flexible for the employer and doesn’t lock in higher fixed costs — which is exactly why employers prefer them.
When choosing between, say, a $10,000 bonus and an $8,000 salary increase, model both: the bonus looks bigger gross, but the compounding salary rise usually wins within two to three years.
Common Mistakes
- Believing in a flat bonus tax rate. There is none — 32%, 37%, 47%: all are just your marginal rate plus Medicare (plus HELP) at your income. The number moves with you.
- Confusing withholding with final tax. A shocking bonus payslip is usually Schedule 5 annualisation, not your real rate. The annual reconciliation in July is the truth.
- Forgetting HELP on the bonus. A $10,000 bonus at $80,000 salary adds $1,500 in HELP repayments under current law — the most commonly missed line.
- Ignoring the bracket push. A bonus that crosses $135,000 (or $190,000) is taxed at two rates; the calculator handles this, but mental maths often doesn’t.
- Spending the gross bonus. Always budget the after-tax figure — the gap is 32–56% depending on income and HELP status.
- Salary-sacrificing after the bonus is earned. Ineffective — the arrangement must pre-date the entitlement.
- Missing the financial-year boundary. A July-paid bonus is next year’s income, with next year’s thresholds and rates.
- Assuming super isn’t paid on bonuses. Most performance bonuses are ordinary time earnings — 12% SG applies on top.
Practical Tips
- Run the calculator before bonus day. Knowing the after-tax figure in advance kills the payslip shock and stops gross-figure budgeting.
- Check your HELP toggle honestly. If you have a study debt, the bonus costs you 15c more per dollar above the threshold — factor it in.
- Time large bonuses across financial years if you have any influence — splitting a $40,000 bonus across June and July can keep both halves out of a higher bracket.
- Put salary-sacrifice paperwork in place early. Before the performance period ends, not after the bonus is announced.
- Reconcile in July. Compare your bonus payslip withholding with the calculator’s liability figure; persistent over-withholding is an interest-free loan to the ATO you can fix with a withholding variation.
Frequently Asked Questions
How much tax do I pay on a $10,000 bonus in Australia?
It depends on your salary and HELP status. On an $80,000 salary with no HELP debt in 2026–27: $3,000 income tax (30% marginal) + $200 Medicare = $3,200 total, leaving $6,800 after tax (32% effective). With a HELP debt, add $1,500 in HELP repayments — $4,700 total, $5,300 after tax (47% effective).
Is there a separate bonus tax rate in Australia?
No. Bonuses are ordinary income taxed at your marginal income-tax rates — the same brackets as your salary. What looks like a special high rate is just your entire bonus landing in your top bracket at once, plus 2% Medicare levy (and HELP if applicable).
Why was so much withheld from my bonus payslip?
Employers withhold on bonuses under the ATO’s Schedule 5 rules, which annualise the lump sum across pay periods. This can look dramatic on a single payslip but usually lands within cents of your true liability — any difference is reconciled when you lodge your tax return, as a refund or a bill.
Do I pay HECS/HELP on my bonus?
Yes. A cash bonus is salary/wages, so it forms part of your HELP repayment income. Under the current marginal system it adds 15c (or 17c) per bonus dollar above the relevant threshold — e.g. $1,500 extra on a $10,000 bonus at $80,000 salary in 2026–27.
Is super paid on bonuses?
Usually yes. Most performance, annual, Christmas and sign-on bonuses are ordinary time earnings, so your employer must pay 12% super guarantee on top — $1,200 on a $10,000 bonus. The only exception is a bonus solely for work performed entirely outside ordinary hours.
Is a bonus taxed in the year it’s earned or paid?
The year it’s paid. Employees are taxed on a receipts basis, so a bonus earned in June but paid in July is assessable in the July financial year — with that year’s brackets and thresholds.
Can I salary-sacrifice my bonus into super?
Yes, but only if the arrangement is entered into before you earn the entitlement to the bonus — it can’t be done retrospectively. Sacrificed amounts count toward your concessional contributions cap ($32,500 in 2026–27) and are taxed at 15% instead of your marginal rate.
Will I get a refund on bonus withholding?
Only if total PAYG withheld across the year exceeds your actual liability. Refunds are common when Schedule 5 withholding overshoots, or when deductions lower your taxable income below what withholding assumed. If the bonus genuinely sat in your top bracket, the withholding is usually about right.
Is a bonus or a salary increase better after tax?
Per dollar in the same year, they’re taxed identically. But salary increases compound year on year and typically accrue super and leave; bonuses are one-off. For lasting wealth, the salary rise usually wins — model both before choosing.
Why does the calculator show a different amount than my payslip?
The calculator shows your annual marginal-rate liability; your payslip shows Schedule 5 PAYG withholding, which annualises the lump sum and can differ slightly. It also doesn’t model the Medicare levy surcharge, tax offsets, or multiple bonuses. Your tax return reconciles everything.
Final Takeaway
A bonus is just salary paid in a lump — taxed at your marginal rate, plus 2% Medicare, plus HELP if you owe it. The formula the calculator uses is disarmingly simple:
Tax on bonus = [Tax(salary + bonus) − Tax(salary)] + 2% Medicare (+ incremental HELP)
For most earners that means 32 cents in every bonus dollar (47 with a HELP debt), bracket pushes at $135,000 and $190,000, 12% super on top from your employer, and a withholding figure on the payslip that usually lands within cents of the real thing.
Use the calculator for the instant answer, then use this guide when the bonus is big enough that brackets, HELP, super caps or timing start to matter. And when the figures decide real money, the ATO’s current-year tables are the final word.